Uncategorized • July 9, 2026

Home Safety Tips Every Child Should Know

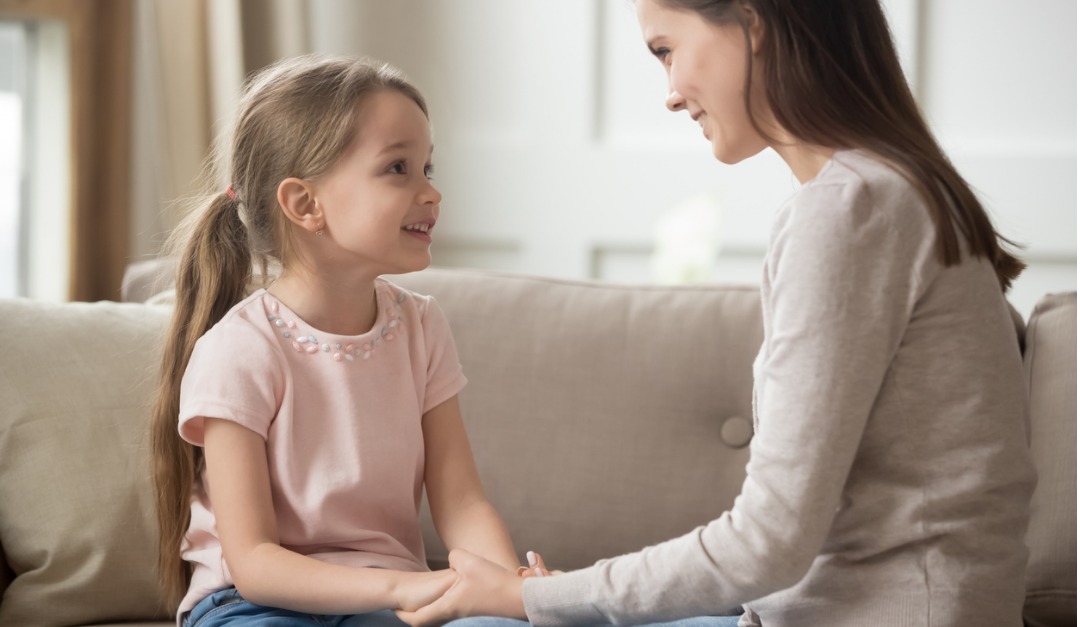
Home safety is an important, even life-saving topic that you should teach your children about at an early age. If you educate your children on basic home safety principles when they’re young, the lessons will stick with them for a lifetime.

Learn to lock a deadbolt. Let your children know that the door should always be locked to keep them safe—even when they’re home. However, it’s important they also know how to unlock it in case of an emergency.

Arm and disarm the home security system. With thousands of burglaries happening each day, it’s wise to invest in a home security system. Teach your children how to arm and disarm the system and what to do should it go off when they’re home or sleeping.

Memorize the escape plan. Just like how elementary schools conduct fire drills, it’s important to have an emergency escape plan at home as well. Walk your children through the house to show them the safest exit routes, and designate a meeting place outside the home where family members should gather if an emergency occurs.

Know important emergency contacts. Post important contact information on the fridge or in an easy-to-access location. Teach young children how to use the phone, dial a number and ask for help. This list could include contacts such as 911, Poison Control, parents’ cellphones, a family doctor, or a trusted friend or neighbor.

Never answer the front door. Children should never answer the front door, especially if they’re home alone. Tell children to alert an adult when the doorbell rings.

Don’t climb on furniture. Heavy furniture, such as TVs, bookshelves and entertainment centers, can tip if children climb on them. You can secure these pieces to the wall studs and add nylon straps to increase security. It’s also important to teach children that climbing on furniture is always dangerous—even if safety measures are in place.

Use medicine safely. Store medicine in locked cabinets that are inaccessible to children. However, should children come across any medicine, they need to know never to consume anything unless it’s given to them by a parent or trusted adult.

Young children often imitate the actions and behaviors of their parents and siblings. Practice the safe habits you want them to emulate, and they’ll likely mimic your moves.
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing


Uncategorized • July 9, 2026

10 Tips to Stretch Your Food Budget

Food is a major expense in any household, and for those on a tight budget, a few dollars saved can make a big difference. ChooseMyPlate.gov offers 10 tips based on planning and smart shopping to help you feed your family while keeping more money in your wallet.

1. Plan, plan, plan. Before you head to the grocery store, plan your meals for the week. Include meals like stews, casseroles or stir fries, which “stretch” expensive items into more portions. Check to see what foods you already have, and make a list for what you need to buy.

2. Get the best price. Check the local newspaper, online and at the store for sales and coupons. Ask about a loyalty card for extra savings at stores where you shop. Look for specials or sales on meat and seafood, which are often the most expensive items on your shopping list.

3. Compare and contrast. Locate the “unit price” listed on the store shelf directly below the product. Use the price to compare different brands and different sizes of the same brand to determine which is more economical.

4. Buy in bulk. It’s almost always cheaper to buy foods in bulk. Smart choices are family packs of chicken, steak, or fish and larger bags of potatoes and frozen vegetables. Before you shop, remember to check if you have enough freezer space to store the extra food.

5. Buy in season. Buying fruits and vegetables in season can lower the cost and add to the freshness. If you aren’t going to use them all right away, buy some that still need time to ripen.

6. Ditch the convenience costs. Convenience foods like frozen dinners, pre-cut vegetables, and instant rice, oatmeal, or grits will cost you more than if you were to make them from scratch. Take the time to prepare your own, and you’ll save.

7. Choose cheaper. Certain foods are typically low-cost options all year round. Try beans for a less expensive protein food. For vegetables, buy carrots, greens or potatoes. As for fruits, apples and bananas are good choices.

8. Cook once to eat all week. Prepare a large batch of favorite recipes on your day off (double or triple the recipe). Freeze the portions in individual containers. Use them throughout the week, and you won’t have to spend money on take-out meals.

9. Get your creative juices flowing. Spice up your leftovers by using them in new ways. For example, try leftover chicken in a stir fry or over a garden salad, or use it to make chicken chili. Remember, throwing away edible food is throwing away your money.

10. Be savvy at restaurants. Eating out can be expensive. Save money by getting the early bird special, going out for lunch instead of dinner or looking for “2 for 1” deals. Stick to water instead of ordering other beverages, which add to the bill.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing


Uncategorized • July 9, 2026

10 Healthy Snack Ideas for Kids

If you were like most kids, you probably dreaded eating fruits and vegetables during your childhood. But now that you’re a parent who understands the importance of healthy food for a child’s well-being, you might find yourself struggling to talk your young kids into doing exactly what you once refused to do.

Pretty ironic, right?

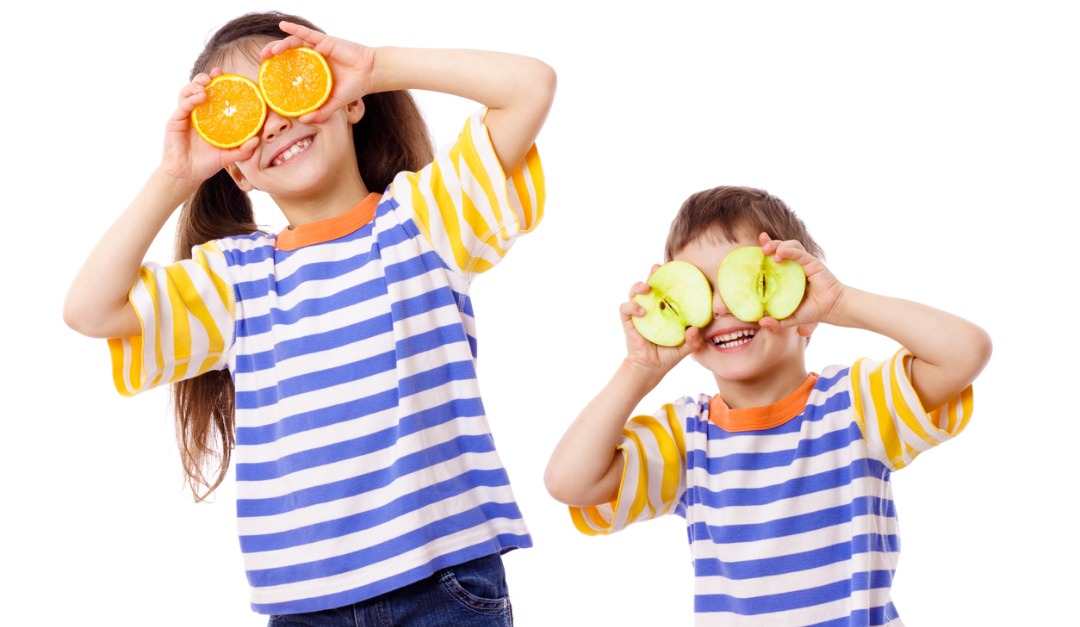
To help you overcome this common challenge, ChooseMyPlate.gov suggests encouraging your children to eat fruits and veggies by trying to make it fun. Depending on their age and abilities, your kids may even be able to prepare their own healthy creations, making it all the more enjoyable for them.

ChooseMyPlate.gov offers these 10 kid-friendly ideas for fruits and vegetables:

Delicious Dippers. Kids love to dip their foods. Whip up a quick dip for veggies with yogurt and seasonings such as herbs or garlic. Serve with raw vegetables like broccoli, carrots or cauliflower. Fruit chunks go great with a yogurt and cinnamon or vanilla dip.

Smoothie Creations. Blend fat-free or low-fat yogurt or milk with fruit pieces and crushed ice. Use fresh, frozen, canned and even overripe fruits. Try bananas, berries, peaches and/or pineapple. If you freeze the fruit first, you can even skip the ice!

Caterpillar Kabobs. Assemble chunks of melon, apple, orange and pear on skewers for a fruity kabob. For a raw veggie version, use vegetables like zucchini, cucumber, squash, sweet peppers or tomatoes.

Personalized Pizzas. Set up a pizza-making station in the kitchen. Use whole-wheat English muffins, bagels or pita bread as the crust. Get tomato sauce and low-fat cheese, and cut up vegetables or fruits for toppings. Let kids choose their own favorites. Then pop the pizzas into the oven to warm.

Fruity Peanut Butterfly. Start with carrot sticks or celery for the body. Attach wings made of thinly sliced apples with peanut butter, and decorate with halved grapes or dried fruit.

Frosty Fruits. Frozen treats are bound to be popular in the warm months. Just put fresh fruits such as melon chunks in the freezer (rinse first). Make “popsicles” by inserting sticks into peeled bananas and freezing.

Bugs on a Log. Use celery, cucumber or carrot sticks as the log, and add peanut butter. Top with dried fruit such as raisins, cranberries or cherries, depending on which type of “bugs” your children want.

Homemade Trail Mix. Skip the pre-made trail mix and make your own. Use your favorite nuts and dried fruits, such as unsalted peanuts, cashews, walnuts or sunflower seeds mixed with dried apples, pineapple, cherries, apricots or raisins. Add whole-grain cereals to the mix, too.

Potato Person. Decorate half a baked potato. Use sliced cherry tomatoes, peas and low-fat cheese on the potato to make a funny face.

Put Kids in Charge. Ask your children to name new veggie or fruit creations. Let them arrange raw veggies or fruits into a fun shape or design.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing


Uncategorized • July 8, 2026

Don’t Make These Car Care Mistakes

Whether commuting to work, dropping the kids off at soccer practice, running errands, going for a joy ride or taking a big road trip, many people rely heavily on their cars for safe transportation. But in order to keep their vehicles running well and protected, it’s important for drivers to take proper care of their cars.

To help ensure you’re not neglecting your ride, Erie Insurance offers these eight major don’ts of car care to remember:

1. Don’t put off recommended maintenance. There’s a reason the car manufacturer gives you that little book when you buy a car. It contains important maintenance guidelines for the age and mileage of your vehicle. By following what it says, you can keep your car running smoothly and safely—and save on having to pay for big repairs later.

2. Don’t ignore warning lights. Most cars come with a check-engine light and other warning lights. If any of them goes off, take your car to a qualified mechanic ASAP.

3. Don’t fail to change the air filter. A fresh air filter keeps your engine running smoothly and improves your car’s fuel efficiency. Most manufacturers suggest you replace your filter every 12,000 to 15,000 miles. (Err on the lower side if you drive in dusty conditions or in stop-and-go circumstances.)

4. Don’t overlook your tires. Regularly check your tires’ air pressure, and keep them properly inflated. Not having the right tire pressure makes for unsafe driving and reduces fuel efficiency. Most vehicles list tire pressure requirements on the driver’s side door post so you know the correct amount of air necessary.

5. Don’t have an unqualified person work on your car. Take the time to find a credible car mechanic that has the skills to fix your vehicle properly. Ask friends and families to recommend a repair shop, and check the Better Business Bureau and online reviews for possible complaints against the company. Verify a mechanic is certified and regularly handles your car’s make and model.

6. Don’t leave keys in the ignition of an unattended car. This is one of the easiest ways to tempt car thieves.

7. Don’t run your gas tank down to empty. Doing so cuts the life of the fuel pump—and puts you at risk of running out of gas before you get to a station.

8. Don’t rarely wash your car. A spotless windshield and clean headlights help ensure you can safely see while driving. Also, a thorough wash helps preserve the exterior of your car, which can ultimately help the vehicle retain its resale value. A good wash is especially important in snow-prone regions during winter, when road salt can do a number on cars.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing


Uncategorized • July 8, 2026

Simple Money Lessons That Will Last Your Child a Lifetime

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing


Carrying cash is becoming less common these days, which can be a nuisance for parents and their children—especially when it comes to paying children their allowance each week.
For many parents, cash allowances are becoming a thing of the past as they instead turn to prepaid debit cards that can be managed directly from their phones. In fact, by simply downloading an app onto their phone for the financial company they’re working with, parents can load money onto a debit card that their child can use at stores, gas stations and anywhere else where debit and credit cards are accepted.
Parents typically sign up for the account and then link their checking account or debit card to fund the child’s debit card.
Along with transferring an allowance, the app can be used to set spending limits, view expenses and automatically match money the child puts into a savings account. Taking this one step further, parents can receive a text message or email when their child makes a purchase—and they can even use the app to disable the card if the child loses it.
Parents can allow children to use their debit card anywhere or can limit it to certain stores and websites. Once these settings are in place, the card will be declined if the child tries to buy something at a non-approved store, or if they try to spend more money than is available on the card.
If the child has their own cellphone, they can get their own version of the app and check balances or get a parent’s permission to buy a certain item. Better yet, some cards can be used at ATMs.
Some financial services allow parents to set chores for the child to complete and then pay the child through the app when the chore has been finished.
If you’re looking to take advantage of this growing trend, some of the financial services that currently offer debit cards for children include Greenlight, Current, goHenry, FamZoo and Akimbo. TD Bank, American Express and Capital One also have debit cards for teens; however, some of these financial institutions require that teens have a checking account with the bank.
The debit cards usually have monthly fees of $5 or so, and some have annual fees. They usually don’t charge extra for adding money onto the card, though parents should carefully read the fee schedule before enrolling in a program because some charge fees for reloading, as well as other services.
Before giving your child a debit card, make sure they understand how it works and how they can check the balance. Use it as a chance to discuss budgeting and saving, and to get them started on a solid financial foot that will hopefully follow them into adulthood.
This article is intended for informational purposes only and should not be construed as professional or legal advice.

Uncategorized • July 8, 2026

5 Signs It’s Time for a New Mattress

A good night’s rest helps you have a good day, not to mention stay healthy and alert. But if your mattress no longer gives you the proper comfort and support, it could mess with the many benefits of quality sleep.

Is it time for you to buy a new mattress? To help you decide, Consumer Reports offers these five signs that your mattress might be shot and worth replacing:

1. It’s a little lumpy. Lumps or deep indentations can happen over time, no matter which materials a mattress is made of. It may also sag, causing you to roll to the center.

2. The foam is failing. Spilling water on certain types of foam may cause damage to the adhesive between the layers, causing them to shift. The foam may also just degrade over time.

3. You’re waking up sore. A worn-out mattress might no longer support your spine’s natural curve, causing stress to other parts of your body as you sleep. If you’re suddenly waking up with unexplained soreness, your mattress might no longer be giving you the support you need.

4. You can feel the foundation. Sleeping in the same spot every night can compress the layers so much over time that you can begin to feel the bed slats or whatever else the mattress is placed on.

5. The springs are poking you. Ouch! If you’ve moved your mattress often or sat in the same spot for extended periods of time (such as when watching TV in bed), you’ve probably pushed its innards out of alignment and a spring might’ve been pushed out of place.

If your mattress is still in good shape, Consumer Reports also offers a few simple tips to help it stay that way.

For example, you should rotate and/or flip your mattress at least twice a year to prevent long-term pressure in certain spots from denting or otherwise damaging those areas. Check the manufacturer’s instructions to learn when and how to perform this duty properly for the type of mattress you own.

Another way to help preserve your mattress is to avoid unnecessary stress caused by, say, sitting at the edge to put your shoes on or bouncing in and out of bed. The gentler you are with your mattress, the longer it’ll likely last.

Sweet dreams!

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing


Uncategorized • July 6, 2026

Should You Use a HELOC to Pay off Credit Card Debt?

Many people struggle to pay off credit card debt. Interest that accumulates each month can make it difficult to make a dent in balances. Juggling multiple credit cards with different minimum payments and due dates can feel overwhelming. Missing a due date can lead to fees and possible damage to your credit score.

If you have lived in your home for several years, you may have built up a large amount of equity. You might be able to use a home equity line of credit, or HELOC, to pay off credit card debt. You could draw from a line of credit at the times and in the amounts of your choosing and consolidate your credit card debt to make one monthly payment instead.

Reasons to Use a HELOC to Pay off Credit Cards
If you have substantial credit card balances with high interest rates, using a home equity line of credit to pay them off might make sense. The interest rate on a HELOC could be significantly lower than the interest rates on your credit cards. That means interest would accumulate at a slower pace and more of each monthly payment would go toward principal, so you could pay off the debt faster.

Paying off credit card balances with a home equity line of credit could help your credit score. Reducing those balances to zero would lower your ratio of debt to available credit, and making HELOC payments on time each month could help you build a positive credit history.

Reasons to Think Twice
You would need to pay closing costs to obtain a home equity line of credit. Talk to your lender to find out exactly how much that would add to your total. Depending on your lender and the interest rates on your credit cards and a HELOC, you might or might not save much money.

A home equity line of credit could be risky. Using your home as collateral means that if you failed to make HELOC payments on time, you could risk foreclosure. That could cause major damage to your credit score.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
Uncategorized • July 6, 2026

Joining the Zero-Waste Movement Is Easier Than You Think

The Environmental Protection Agency estimates that the average American generates nearly 4.5 pounds of trash on a daily basis, more than half of which goes to a landfill.

If you’re looking to reduce your net trash output with the ultimate goal of joining the zero-waste movement, there are a variety of small steps you can take today.

Refuse
Start by not bringing any items into your house that you don’t need. This includes company giveaways, such as a promotional tote bag from a work conference, free pens that make their way into your hands, plastic bobblehead figures from the ballpark and plastic utensils that come with your takeout order.

Reduce
Buying fewer things will ultimately save you money. Before buying new clothing, electronics, home appliances or anything else, ask yourself if you truly need it.

Reduce your reliance on single-use items such as plastic water bottles, individual yogurt cups and disposable plastic razors. When you do buy something, take advantage of reusable canvas grocery bags.

You can also lower the thermostat in your home and lower your energy usage, plan meals each week so that less food is wasted, and take advantage of public transportation so that you use your car less.

Reuse
Picking up a new skill such as sewing can help you repair some of your clothes and give them a longer life. If there are too many holes in a shirt to repair, use it as a rag instead of using paper towels. Reusing items for something other than their original purpose is a chance to get creative and see just how far you can go.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
Uncategorized • July 6, 2026

Should You Prioritize Paying Off Debt or Saving for Retirement?

Many Americans are burdened by debt and have little or no retirement savings, and people who want to get out of debt and save money for the future often don’t know where to begin. Some financial experts might offer general advice that doesn’t fit every situation. The correct approach depends on several individual factors.

Burdens of Debt and Benefits of Saving
High-interest debt, particularly from credit cards, can weigh you down. Interest can keep building up month after month, and making only minimum payments can cause you to feel as though you’ll never be free. Paying as much as you can every month can help you eliminate debt faster.

On the other hand, the key to building up a retirement account is time. Making regular contributions, even small ones, and allowing interest to accumulate for decades can help you build a sizable nest egg. If your employer matches your contributions, your savings will grow even faster, especially if you contribute the maximum allowed.

Which Approach Is Right for You?
If you’re relatively young and saddled with high-interest debt, it makes sense to tackle that first. Doing so will allow you to stop spending money on interest and then focus on other long-term priorities. Once your debt has been eliminated, you’ll still have several decades to save for retirement and will be able to contribute a significant amount each month.

If your debts have low interest rates and you have little or no money saved for retirement, contributing to a 401(k) or IRA first makes sense, especially if you’re getting older. The more time your retirement savings get to accumulate interest, the better off you’ll be down the road. The amount of money you’ll gain in interest on your savings will likely be much higher than the amount you’ll pay in interest on your debt.

If you have debt with moderate interest rates, some retirement savings and decades left to save, strike a balance between paying off debt and saving for the future. Look at your monthly income and expenses and create a plan that addresses your priorities of saving for retirement and eliminating debt so you can work toward both goals simultaneously.

Figure Out What Makes Sense for You
When it comes to financial questions, one-size-fits-all advice isn’t appropriate. Whether you should save for retirement, pay off debt first or do both at the same time will depend on the amount of debt you have, your interest rates, how much you have saved for retirement and how much longer you plan to work. Consider your individual circumstances to decide which approach is right for you.

This article is intended for informational purposes only and should not be construed as professional or legal advice.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
Uncategorized • July 6, 2026

Learn Anything When the Experts Can Come to You

Want to master scallopine? Write a best-seller? Play the violin like a virtuoso? You can learn the basics from world-class connoisseurs without ever having to leave home.

Through the online magic of MasterClass.com, you can study screenwriting with Martin Scorsese or acting with Helen Mirren. Learn the art of photography with Annie Leibovitz, or the art of magic and sleight of hand with the fabled Penn and Teller.

You can play the violin with Itzhak Perlman, perfect your jazz piano with Herbie Hancock, or learn to write a best-selling thriller with Dan Brown or David Baldacci. It’s all there, at surprisingly low rates, with curricula ranging from the art of the deal to the art of cooking with Wolfgang Puck.

If cooking is your thing, you can also take lessons live in your own kitchen from culinary experts–chefs who will come to you in New York, Chicago, D.C., Los Angeles, Connecticut, New Jersey or San Diego. Find them online at TableAtHome.com, invite a few friends over and dine in. Brush up on barbecue, brunch or international cuisines, with live instruction among your own pots and pans.

Or maintain your privacy and learn to cook one-on-one via Skype with an internationally based chef. Just hang up your keys, open a bottle of wine, and video-call a chef from around the world. Master the art of paella with step-by-step instruction from an executive chef in Spain, carbonara from an Italian chef, or jambalaya direct from New Orleans. Choose your faves at TheChefAndTheDish.com, and get personal attention with a 90-minute lesson.

Personal training has new meaning these days. So indulge, and follow your passion.

#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie., #MoveWithKathie.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing