Uncategorized • August 14, 2026

Simple Ways to Save Money on Braces

While the cost of braces varies by type, in general, the traditional metal braces that most people get to straighten their teeth cost anywhere from $3,000 to $7,000.

If braces are in the future for you or another member of your family, figuring out how you’re going to pay for them is critical when it comes to ensuring that you have enough money set aside to cover the expense when the time comes.

For those with dental insurance, the first thing you’ll want to do is look into what’s covered—and what’s not. After insurance, here are some other ways to save on the cost of braces:

Dental Savings Plans
Also called dental discount plans, these are alternatives to traditional dental insurance. You pay an annual fee upfront and get a dental discount card to get discounts at local dentists. Savings range from 10 – 60 percent.

Payment Plans
Orthodontists know that braces cost a pretty penny, so many of them offer monthly payment plans to make paying for them easier. Before agreeing to a payment plan, be sure to get it in writing.

Plan Ahead
When it comes to children needing braces, it’s often easier to plan ahead because their dentist will most likely tell you well ahead of time that your child will need braces at some point in the future. This will give you time to budget for any upcoming expenses associated with getting and having braces as you can begin putting money aside on a monthly basis. If it turns out your child doesn’t need braces, chances are the money will be needed for some other medical expense in the future.

Dental Schools
If you’re lucky enough to leave near a university that has a dental or orthodontic school, you can often get a reduced price on dental care. The work done by students is fully supervised by experienced orthodontists. Be sure to check out the American Association of Orthodontists (AAO) website for a list of accredited programs in your state before making an appointment.

Go Shopping
Chances are there are many orthodontists in your area. If you don’t like the price or services offered at one, take the time to shop around. Prices can vary tremendously, so ask family and friends for recommendations—and don’t accept the first offer you’re given.

Avoid Third-Party Plans
Some dentists offer third-party payment plans, which often charge high interest and should be avoided. If your dentist doesn’t offer an interest-free payment plan on their own, you may want to consider asking your bank or credit union for a loan.
Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,
Uncategorized • August 10, 2026

Transitioning from a Car Lease to a Purchase

Leasing can be a smart way to test out a car for a few years without buying it. A lease can give you all of the latest technology and some time to determine if you like the car enough to buy it.

If you want to buy it before the lease expires, read the terms of the lease agreement to see if an early buyout costs extra, typically charged in finance fees. It may be worthwhile to wait until the lease ends.

To make sure you’re getting a good deal, research the different ways the car is valued. The first is retail value, which is how much you’d pay to buy it from a dealer. The second is wholesale value, or how much the car would cost at auction. Pricing is available at various websites such as Kelley Blue Book and Edmunds. Be sure to compare the same make, model and mileage.

Compare these numbers with the residual value—that’s an estimate of the car’s value at the end of the lease and will be stated in the lease agreement. A purchase-option fee may be added. Your research will help you compare your car’s value to the residual value to see if it’s close to what you’ve estimated it to be.

Don’t contact the leasing company first if you’re thinking of buying. They’ll come to you, usually 90 days before the lease expires. If they already know you’re interested in buying, you lose an advantage when negotiating.

Start the negotiations by finding financing elsewhere, since that is where the leasing company is likely to start as a way to make more money off you. Check with your bank and other lenders for lease-buyout loans.

Some leasing companies may have a policy against negotiating a buyout price, but it doesn’t hurt to ask. Request that they waive the purchase-option fee and offer financing discounts and other incentives to buy.

Remember that you have some leverage when offering to buy a leased car. You can walk away and find another car, leaving the leasing company the work of finding another buyer for the car when they already have a ready and willing buyer in front of them. Remind them of this opportunity and how much higher their price is than what you’ve found elsewhere, and you hopefully can move them toward a deal.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,


Uncategorized • August 10, 2026

4 Must-Have Coffee Table Books for Design Lovers

As great as it is to view striking architecture and design on our tablets or laptops, nothing beats leafing through the glossy pages of a beautiful coffee table book. These large, oversized books often provide a transportive experience when we dive into them. And when they’re not being used, they contribute to the aesthetic of a room. For design lovers who are in search of the perfect book to adorn their coffee table, here are four fantastic options that are sure to please.

Buckingham Palace: The Interiors
Whether you’re a history buff, design enthusiast, or simply can’t get enough of the royal family, this rare glimpse inside of Buckingham Palace is like a masterclass in Regency, Victorian and Edwardian styles. In this book, artist and designer Ashley Hicks captures ceremonially spaces throughout the palace that are furnished with priceless treasures from the Royal Collection.

Off the Grid: Houses for Escape
On the surface, this is a book featuring imagery of stunning homes in remote locations around the world. Once the vibrant photography draws you in, however, the reader gets to learn about the creative architects and innovative technologies that enable these residences to significantly reduce their carbon footprint and run on renewable energy. For anyone who is passionate about eco-friendly design, this deserves a spot on your coffee table.

In Comfort and Style
Designer to the stars Estee Stanley opens up about her process of creating living spaces that epitomize laid-back luxury. Having worked with such celebrities as Patrick Dempsey, Ellen Pompeo and Justin Timberlake, you can rest assured that she knows her stuff and this book has the photography to prove it.

Love Affairs with Houses
Bunny Williams is nothing short of an icon in the world of interior design. Her new book, Love Affairs with Houses, is an exploration of 15 homes she has decorated and, of course, fallen in love with. For anyone with a passion for classic aesthetics, this is an insightful case study from one of the most renowned interior designers there is.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,
Uncategorized • August 10, 2026

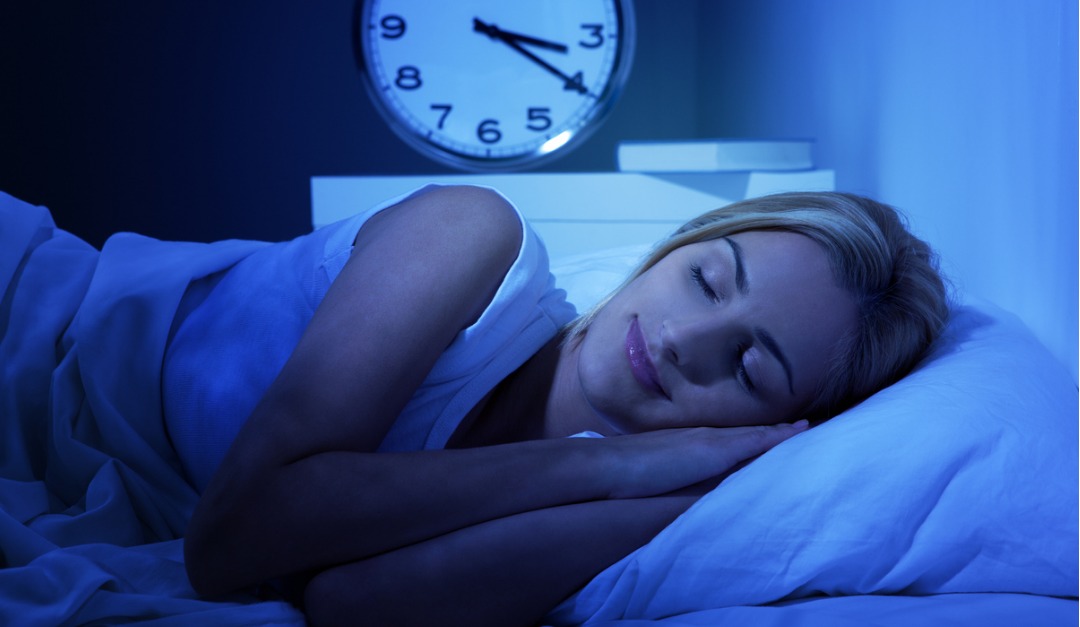
10 Tips for Getting a Good Night’s Sleep

Do you find it tough to roll out of bed every morning? Are you yawning, feeling groggy and chugging cups of coffee throughout the day? News flash: You probably aren’t getting enough sleep.

Sleep is essential for your mental and physical health. Most adults need 7 to 8 hours of shuteye each night, and the quality of sleep you get is just as important as the amount. If you’re having trouble catching z’s, making some changes to your routine might help. The National Heart, Lung and Blood Institute, whose focus also includes sleep disorders, offers the following 10 tips for getting a good night’s sleep:

1. Stick to a sleep schedule. Go to bed and wake up at the same time each day—even on the weekends.

2. Exercise, but not too late in the day. Try to exercise at least 30 minutes on most days but not later than 2 to 3 hours before your bedtime.

3. Avoid caffeine and nicotine. The stimulating effects of caffeine in coffee, soda, certain teas and chocolate can take as long as 8 hours to wear off fully. Nicotine is also a stimulant.

4. Avoid alcoholic drinks before bed. A “nightcap” might help you fall asleep, but alcohol keeps you in the lighter stages of sleep. You also tend to wake up in the middle of the night when the sedating effects have worn off.

5. Avoid large meals and beverages late at night. A large meal can cause indigestion that interferes with sleep. Drinking too many fluids at night can cause you to awaken frequently to urinate.

6. Avoid medicines that delay or disrupt your sleep, if possible. Some commonly prescribed heart, blood pressure or asthma medications–as well as some over-the-counter and herbal remedies for coughs, colds or allergies–can disrupt sleep patterns.

7. Don’t take naps after 3 p.m. Naps can boost your brain power, but late afternoon naps can make it harder to fall asleep at night. Also, keep naps to under an hour.

8. Relax before bed. Take time to unwind. A relaxing activity, such as reading or listening to music, should be part of your bedtime ritual. If possible, take a hot bath before bed; the drop in body temperature after a soak may make you feel sleepy, and the bath can help you relax.

9. Create a good sleeping environment. Address anything in your bedroom that might distract you from sleep, such as noises and bright lights. Consider keeping electronic devices, such as TVs, computers and smartphones, out of the bedroom. Also, keeping the temperature in your bedroom on the cool side can help you sleep better.

10. Don’t lie in bed awake. If you find yourself still awake after staying in bed for more than 20 minutes, get up and do some relaxing activity until you feel sleepy. The anxiety of not being able to sleep can make it harder to fall asleep.

If you continue to have trouble sleeping or consistently feel tired despite spending enough time in bed each night, talk to your doctor. A good night’s sleep is vital for your well-being and ensuring you’re recharged and ready to take on the day.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,


Uncategorized • August 10, 2026

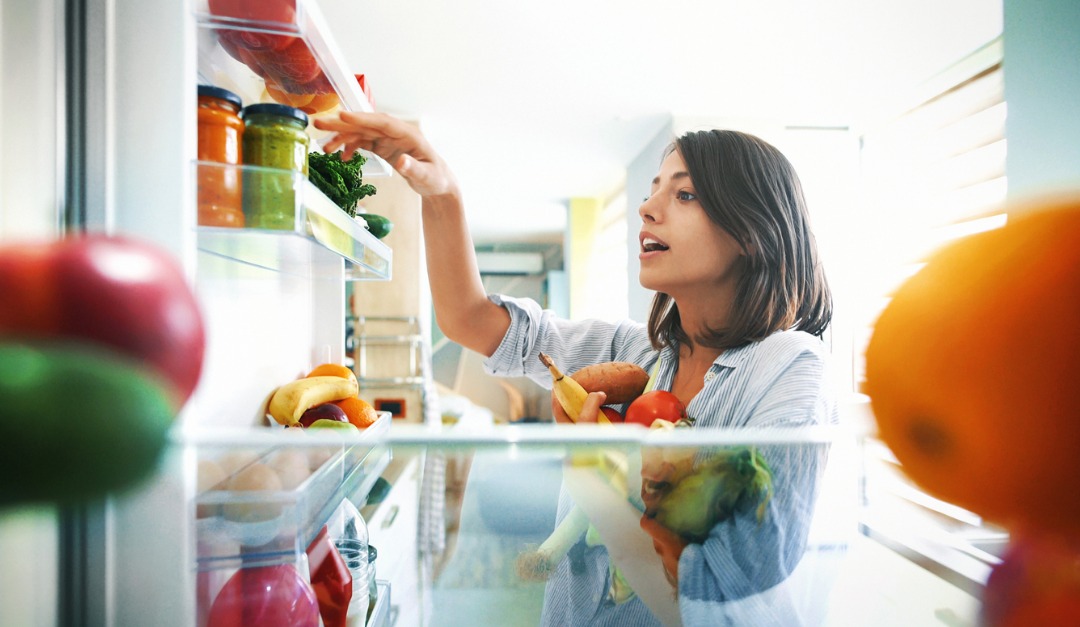
A 10-Point Guide to Healthy Meals

Most everyone knows a healthy diet is important for a healthy body. But eating the right foods every day might be easier said than done–especially with so much tempting junk food available! If you’re looking to improve your diet, start by making some small changes and learning the keys to healthy eating.

Try to include all the major food groups–fruits, vegetables, grains, dairy and protein–as part of your meals and snacks daily. You’ll also want to limit added sugars, saturated fat and sodium. For further guidance, check out these 10 tips from ChooseMyPlate.gov for building healthy meals and meeting your eating needs throughout the day:

1. Make half your plate veggies and fruits. Vegetables and fruits are full of nutrients that support good health. Choose fruits and red, orange and dark-green vegetables, such as tomatoes, sweet potatoes and broccoli.

2. Include whole grains. Aim to make at least half your grains whole grains. Look for food labels indicating the product is 100-percent whole grain or whole wheat. Whole grains provide more nutrients, including fiber, than refined grains do.

3. Don’t forget the dairy. Complete your meal with a cup of fat-free or low-fat milk. You’ll get the same amount of calcium and other essential nutrients as whole milk but fewer calories. Don’t drink milk? Try drinking soymilk or include low-fat yogurt in your meal or snack.

4. Add lean protein. Choose proteins such as lean beef, pork, chicken or turkey, as well as eggs, nuts, beans or tofu. Twice a week, try to make seafood the protein on your plate.

5. Avoid extra fat. Using heavy gravies or sauces will add fat and calories to otherwise healthy choices. Try steamed broccoli with a sprinkling of low-fat parmesan cheese or a squeeze of lemon.

6. Get creative in the kitchen. Whether you’re making a sandwich, stir-fry or casserole, find ways to make them healthier. Try using less meat and cheese, which can be higher in saturated fat and sodium, and including more veggies that add new flavors and textures to your meals.

7. Take control of your food. Eat at home more often so you know exactly what you’re eating. If you eat out, check and compare the nutrition information. Choose options that are lower in calories, saturated fat and sodium.

8. Try new foods. Keep it interesting by picking out new foods you’ve never tried before, such as mango, lentils, quinoa, kale or sardines. You may find a new favorite! Trade fun and tasty recipes with friends, or find some online.

9. Satisfy your sweet tooth in a healthy way. Indulge in a naturally sweet dessert dish—fruit! Serve a fresh fruit salad or a fruit parfait made with yogurt. For a hot dessert, bake apples and top them with cinnamon.

10. Remember that everything you eat and drink matters. The right mix of foods in your meals and snacks can help you be healthier now and into the future. Small, practical changes in how you eat can improve your diet and add up to big wins over time.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,


Uncategorized • August 10, 2026

3 Tips for Ditching Coffee

Looking to kick the caffeine? While a moderate amount of the buzzy stuff has been shown to have heart benefits, it’s easy to overdo it or find yourself addicted to that morning jolt. If you’re looking to slay your latte habit, consider the following tips.
Time it right. Quitting anything you’re addicted to is challenging, and coffee is no exception. Choose a time that will support your withdrawal. The Monday your big work project is due? Not the best time.
A long weekend is a great time to begin so that you can distract yourself or, at worst, lay down with that 3 p.m. headache.
Find a suitable substitution. If you don’t want to quit cold turkey, you can find a substitution. Some people like to guzzle tea, water, or even decaf coffee as they wean themselves off that fresh brew. A more overlooked substitution is raw cacao. Sold in many grocery stores and available online, cacao nibs pack a caffeine punch that can help wean you slowly off the java juice. Warning: They’re bitter, and some people enjoy them more than others.
Warn everyone. Make sure to tell your friends, partner, and close colleagues you’re cutting coffee. This way, they can support you by nixing that afternoon coffee invite, and they’ll understand if you’re a bit groggy or snippy for the first few days.
Interested in housing and real estate tips? Feel Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,free to contact me directly.

Uncategorized • August 6, 2026

How to Balance Saving for Retirement and Saving for Your Kids’ College Education

Many people are on a tight budget and don’t save as much as they should for retirement. If you have children and you want to save for their education, things can get even trickier. Here are some tips to help you prioritize and accumulate enough savings.

Make Logical Decisions
You have likely heard stories about recent college graduates who are overwhelmed with student loan debt and don’t want your own kids to wind up in the same boat. That’s completely understandable, but don’t let those feelings cause you to focus so much on saving for your kids’ future that you neglect to prepare for your own.

Your kids can choose from a wide array of colleges and majors. They can start off at less expensive schools to save money and transfer to more expensive institutions later. They can receive grants and scholarships, take out loans and work during the school year and vacations to pay for their education.

You will have far fewer options to cover your retirement costs. If you’re older and not in good health, you probably won’t be able to work full-time and you may have expensive medical bills. You won’t be able to take out loans to cover all your expenses and you don’t want your kids to shoulder the burden of supporting you financially.

If you need to save for retirement and you also want to set aside money for your children’s education, it’s important to make decisions based on logic, rather than emotion. Focus on saving for your own future before saving for your children’s. This isn’t selfish; it’s realistic and practical.

Retirement and College Savings Strategies
If your employer offers a 401(k) or another retirement plan with a match, contribute as much as you can. Any match you receive is essentially free money, so try to contribute enough to get the full match. Whether your employer offers a retirement plan or not, you can also open a Traditional or Roth IRA. Explore the tax implications of each to decide which would make more sense given your financial circumstances.

You can also open a 529 college savings plan for each of your children. Depending on where you live, you may enjoy significant tax advantages. The sooner you start saving, the more time the money will have to grow. You can contribute money yourself and encourage family members to make contributions to the accounts instead of giving your children money for birthdays and holidays. Even small amounts can add up over time.

Seek Professional Advice
Saving for retirement and for your children’s college education are both important goals, but with limited funds, you will need to set priorities. Focus on your own retirement first and then save as much as you can for your children’s education. If you need help deciding which plans would be best for your family and figuring out how to fit long-term savings into your monthly budget, talk to a financial advisor.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,


Uncategorized • August 6, 2026

An Informative Guide to Borrowing Against Your Life Insurance Policy

Life insurance doesn’t have to only be used when you pass away. A permanent life insurance policy gains cash value, which is money you can withdraw while you’re still living.

The money you borrow from the policy reduces the death benefit of the policy if you don’t repay the loan while you’re living. If the loan isn’t paid back before the insured person passes away, the loan amount plus any interest owed is subtracted from the amount the beneficiaries would receive from the death benefit.

Permanent life insurance policies, such as whole life and universal life, build up cash value that collects interest. Only a partial amount of the total cash value can be borrowed, unless you want to surrender the entire policy and take the entire cash value.

Where does the cash value come from? The monthly premiums paid into the policy exceed what’s needed for the death benefit, and that money is invested by the insurance company. A cash value is created after a few years.

It can be borrowed against, and the policy is collateral for the loan. Common uses for these loans are paying off a mortgage, retirement income, paying debts and paying for college.

To start, verify with your insurer that you have enough cash value to take out a loan. They will give you forms to complete, and after you get the loan, you can keep up loan payments if you want. The loan amount doesn’t count as taxable income and interest rates are lower than a traditional loan.

If the loan isn’t repaid while you’re living, the death benefit could be reduced. If the interest on the loan and the unpaid loan balance exceeds the policy’s remaining cash value, you could lose your policy.

A term life insurance policy, which is cheaper and used by most people, can’t be borrowed against. Term policies don’t have a cash value and the policies expire after a certain term, usually from one to 30 years.

Cash value from an insurance policy can also be used to pay the insurance premiums if you’re short on cash, according to the Insurance Information Institute. This can happen if you face unexpected expenses, such as a hospital stay, and can’t afford to make payments on an insurance policy. If you use all of the cash value funds, the policy could lapse, and your life insurance coverage could end.

If your beneficiaries don’t need the money from an insurance policy, then borrowing against it can be a good way to pay immediate bills and fund retirement. But if you think they will need the money, then either find another type of loan or pay back the insurance policy loan over time.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,


Uncategorized • August 6, 2026

How to Choose the Right Pet for You

Are you thinking about getting a pet? Owning and taking care of an animal is a huge commitment filled with responsibilities and expenses. Some pets more so than others. Although you or a family member may have a particular animal in mind, the American Veterinary Medical Association suggests you consider the following to help ensure you choose the right pet for your household and circumstances:

Do you already have a pet? If so, will your current pet accept another pet of the same or a different species? If you’re uncertain, your veterinarian can help you answer this question.

What are you looking for in a pet? Do you want a lap warmer? A running buddy? Or a pet that’s easy to care for? This will affect your pet choice.

Who will care for the pet? Consider the abilities and availability of the caretaker. If you have young children, a pet that’s active at night wouldn’t be as good a choice as one that’s active during the time your child is awake. Although it’s good to involve children in caring for pets if you have them, it’s unrealistic to expect a child to be solely responsible for any pet’s care and welfare.

Do rules limit your choice? If you rent, your landlord may restrict the type or number of pets you can have. Condominium and homeowner associations may have similar restrictions. If you live in a city, your choice of pet may be very different from your choice if you lived in the suburbs or the country. Some types of pets aren’t allowed by local ordinances. Consider also the amount of exercise your pet will need and whether your living arrangements accommodate that need.

Can you provide enough attention and a life-long commitment? Different species and breeds of animals have differing needs for companionship and attention, as well as differing life expectancies. For example, some larger birds have been known to live more than 100 years! Do your research to ensure you have a realistic understanding of the commitment you’re making when you get a particular type of pet.

Can you afford the pet? Think of the needs your pet will have for food, housing, socialization, exercise, grooming and veterinary care, and make sure you can afford and are willing and able to provide them. Some pets, such as reptiles, amphibians, pocket pets and birds, require special veterinary care, so make sure there’s a veterinarian in your area who can provide that care.

How long will you be present? Some pets need more frequent exercise or feeding and might not be a good choice for owners who spend a lot of time away from home by working long hours or traveling frequently.

A cat, dog, bird, fish, rabbit, rodent, ferret, reptile–even a horse. There are so many different types of pets to consider. If you’re still unsure which is right for you, do some research or consult a veterinarian.

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,


Uncategorized • August 3, 2026

How to Avoid Credit Card Interest

The typical credit card charges about 16 percent interest per year on balances, effectively adding $16 to each $100 in expenses that are left on a credit card. Some charge as much as 29 percent if you’re late on a payment and have to pay penalty interest.
Avoiding a credit card balance by paying the bill before the due date each month is the best way to avoid such extra charges—but that’s rare. For every five credit card accounts, more than three carry a balance from one month to the next, according to a Federal Reserve payments study.
Here are some ways to avoid paying credit card interest:
Know the Grace Period
Most people think they only have a month to pay off a credit card bill. By knowing their card’s grace period, they can see how much more time they have. A grace period is the time allotted to pay off your credit card bill without incurring any interest. It starts on the last day of your billing cycle and runs through the due date for that cycle.
Knowing what your credit card’s billing cycle is can give you about three more weeks to pay off purchases. The key, however, is not forgetting what the payment due date is and paying the full amount by that due date.
For example, a credit card’s billing cycle may start on the twenty-third of one month and end on the same day a month later, such as May 23 – June 23. The payment due date could be July 17. In this case, the grace period might be June 24 to July 17—about three weeks long. Instead of having a month to pay the bill off, you now have about seven weeks.
Pay as You Buy
If you really want to be diligent about avoiding interest charges, pay off charges on your credit card as soon as you make them.
Credit card companies are happy to accept payment at any time, even multiple times in a month. So, every time you make a purchase with your credit card, immediately transfer money from your bank to the credit card company for the same amount. You can often do this through your credit card’s app on your phone, or you can set up weekly payments of a certain amount if you expect to make a certain number of purchases per week.
Pay in Full Each Month
Paying off the credit card bill in full each month is the best way to avoid interest charges. Do whatever it takes to pay it by the due date. Send yourself email and other alerts, keep track of purchases to ensure you have enough money in your checking account to pay the bill, and stick to a budget.Caution Sign – Higher Interest Rates Ahead

Kathie Aldunate Realtor
Century21 New Millennium
1730 West Street, Annapolis.21401
C:443-717-0292
O:410-266-905
.#AnnapolisRealtor #AnnapolisHomes. #AnneArundelCountyLiving #AnnapolisRealEstateMarket., #OdentonHomes, #SeniorDownsizing
#AnnapolisRealEstateMarket, #AnneArundelCountyLiving, #CroftonRealEstate, #DreamHome, #GambrillsRealtor, #MarylandRealEstate, #MoveWithKathie.,